
The third quarter of 2026 belonged to the megadeals of gaming, according to a quarterly gaming M&A and investment report by Drake Star Partners.
During the quarter, Electronic Arts went private in a $55 billion deal. Paramount bought Warner Bros., including its billion-dollar-a-year gaming business, for $110 billion. And China’s Alibaba exited its stake in Lingxi games for more than $1.5 billion.
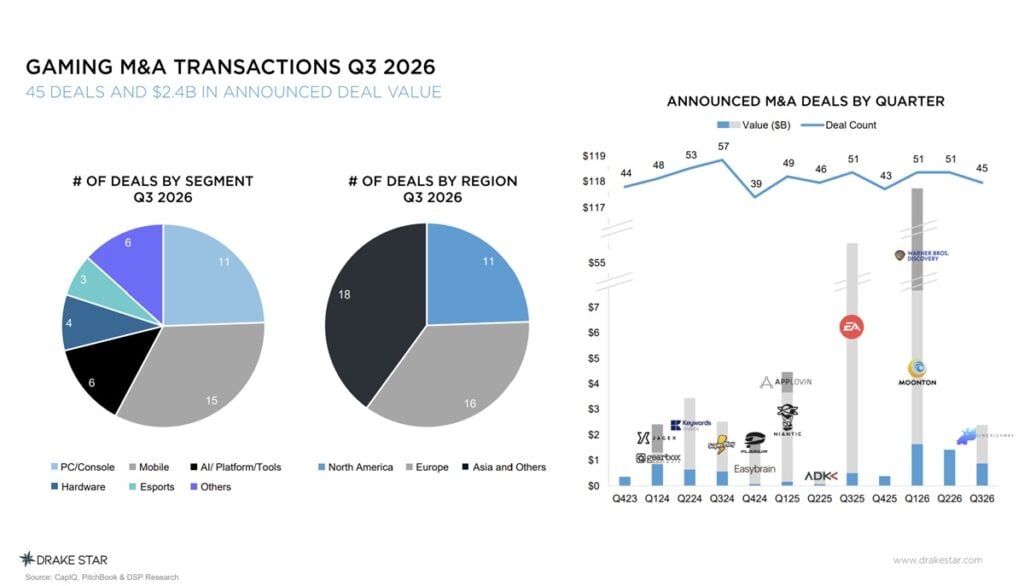
During the quarter, gaming stocked rallied by about 15% in value in the public stock markets. And underneath the big deals, 45 M&A transactions added up to $2.4 billion in value during the quarter, said Michael Metzger, managing partner at Drake Star Partners.
As for upcoming attention grabbers for gaming, Metzger said that the pending November 19 launch of Grand Theft Auto VI could be so big it could push gaming higher into mass culture and draw more investor to the sector, resulting in a more positive investment climate. However, layoffs were still pervasive during the quarter with major layoffs or studio shutdowns happening virtually every week during Q3. That’s one the issues we will focus on at our GamesBeat Next 2026 event coming on November 2-3 in San Francisco.
“Investor interest in he sector should build into year-end, with GTA VI’s November 19 launch likely to lift sentiment across publishes, platforms and the wider gaming ecosystem,” the report said.
On the other hand, just Take-Two and Rockstar Games will be the primary beneficiaries of the revenue growth.
“We expect gaming M&A to stay resilient through year end, as strategic and financial buyers pursue scale, proven IP and recurring revenue, and large groups continue divesting non-core assets,” Metzger said.
He also said that private capital is likely to stay concentrated in AI and tech-related opportunities, especially development tools, 3D content creation and infrastructure, with investors favoring defensible technology and clear traction.
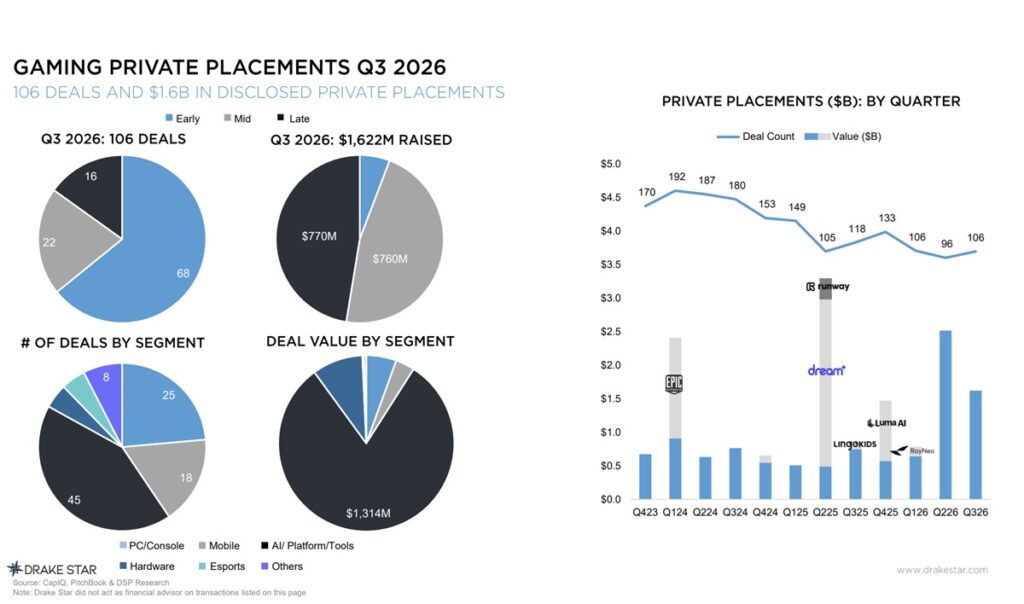
As for private investments, game companies raised $1.6 billion in the quarter in 106 private rounds, with AI and tools capturing more than 80% of the capital.
The Drake Star Global Gaming Report Q3 2026 analyzes gaming dealmaking and public markets in the third quarter of 2026 and outlines what to expect for the rest of the year and beyond.
Highlights of the quarter
Gaming stocks roared back in Q3’26. The Drake Star Gaming Index jumped about15% in the quarter, powered by Western and PC/console names. The standouts since the start of 2025: Everplay (+112%) thanks to the successful launch of Wardogs in the quarter; accessories maker Corsair, up 105%; and Unity (+82%). It’s worth noting, however that stock market growth for the index peaked in late 2025, declined through the first half of 2026 before finally rallying Q3 2026 to finish 9.6% above its January 2026 level.
Gaming activity was concentrated in Asia and driven largely by divestitures, led by Alibaba’s $1.5 billion+ sale of Lingxi Games to Trustar Capital and Kunlun Tech’s ~$105 million sale of mobile chess and card developer Xianlai Interactive Entertainment. Webtoon also agreed to buy a 60% stake in South Korean game developer RI Games Holdings for $100 million, expanding its gaming pipeline based on popular webcomic IP.
Other notable deals included Corsair’s $50 million acquisition of sim racing hardware maker Trak Racer (Drake Star acted as the exclusive financial advisor to Trak Racer) and Tripledot Studios’ $40 million acquisition of Supersonic from Unity.
The largest private game financing rounds were Meshy ($400M), General Intuition ($220M), Blacknut ($215M), Nex ($150M) and VAST’s Tripo AI ($150M), while PixVerse, Stability AI, Delphi Interactive, Circle Games and W4 Games also raised notable rounds.
Stonx also made a comeback, as GameStop announced a private exchange of $1.4 billion in convertible senior notes for equity, reducing its long-term debt without using cash proceeds. Embracer Group also secured a $200 million credit facility to refinance existing debt and support general coporate purposes ahead of the planned Fellowship Entertainment spin-off in 2027.
Over the last 12 months, Arcadia and General Catalyst topped large-fund activity, Impact46, Merak and SISU were the most active seed investors, and Sony and Kakao set the pace among strategics.
Eight new funds totaling over $800 million were announced in Q3’26, led by Vgames’
$500 million user-acquisition financing platform and Makers Fund IV.
Outlook for gaming financials
Drake Star Partners expects gaming M&A to stay resilient through year-end, as strategic and
financial buyers pursue scale, proven IP and recurring revenue, and large groups continue divesting non-core assets.
Private capital will likely keep flowing to the picks and shovels of gaming: AI, dev tools, 3D content creation and infrastructure, where investors find proven traction and hard-to-replicate tech.
GTA VI lands November 19, and the sector’s biggest launch in over a decade should jolt investor sentiment across the entire gaming ecosystem, from publishers and platform holders to studios, tools and services providers, heading into 2027, the report said.
North America led the way in M&A deals at 18 in the quarter, compared to 16 in Europe and 11 in Asia.
So far in 2026, NetEase’s stock has risen the most in percentage terms, up 50.6% ear to date, followed by 46.5% for Corsair, 42.7% for NCSoft, 41% for EA, and 35.4% for Take-Two. The weakest stocks so far in 2026 (measured through September 30) are Ubisoft, down 58.3%; Kakao Games, down 52.6%; Shift Up, down 47.4%; Playtika, down 41.8%; and GungHo, down 31.9%.
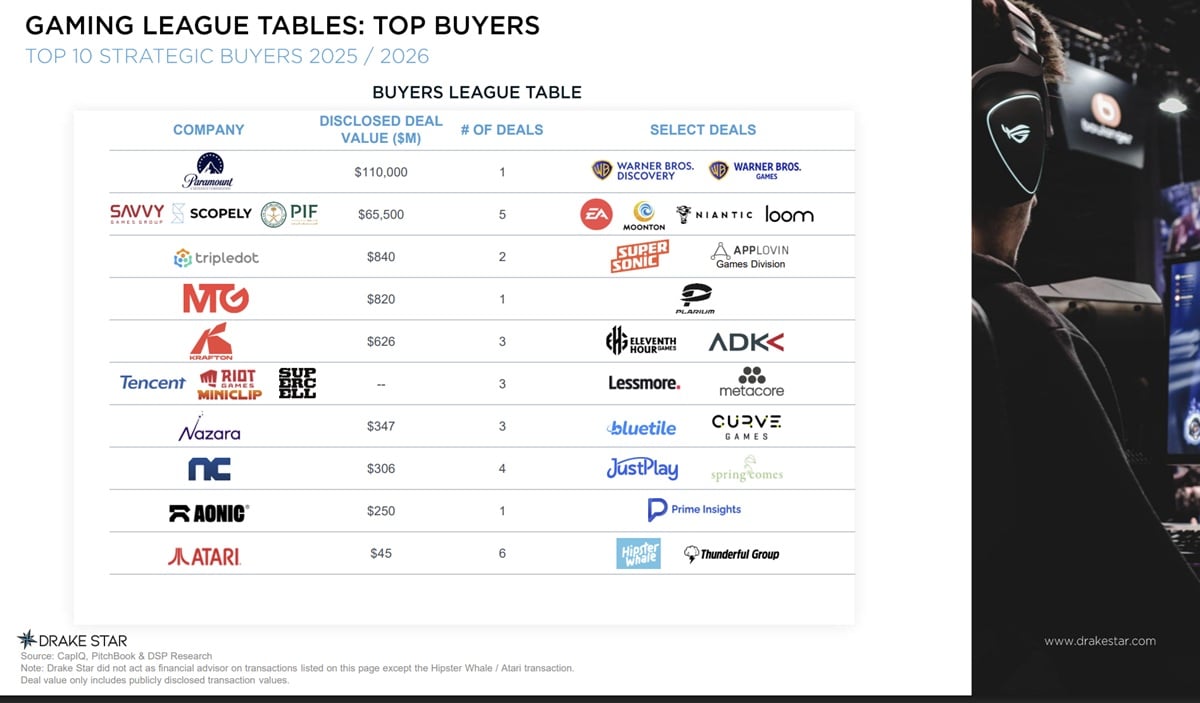
The top buyers of gaming from a strategic view include Paramount with its $100 billion Warner Bros. deal; Savvy/Scopely and the Saudi Arabia Public Investment Fund at $65.5 billion in deals for EA, Moonton, Niantic and Loom; and Tripledot, which bought Supersonic for $40 million and AppLovin’s gaming division for $800 million.
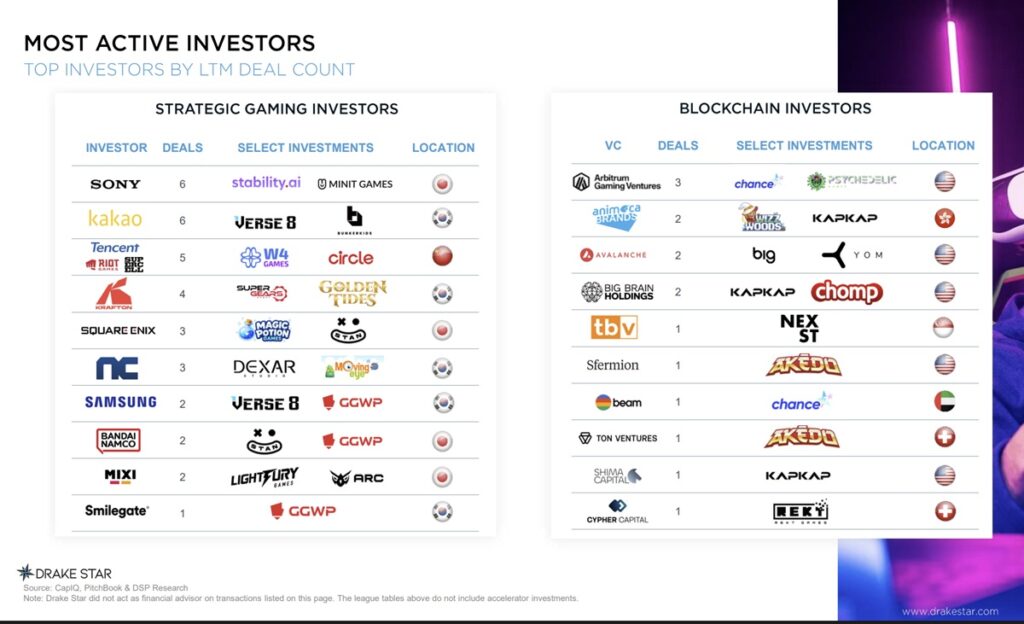
The most active strategic gaming investors by deal count include Sony with six deals; Kakao with six deals, Tencent with five deals’ Krafton with four deals and Square Enix with three deals.
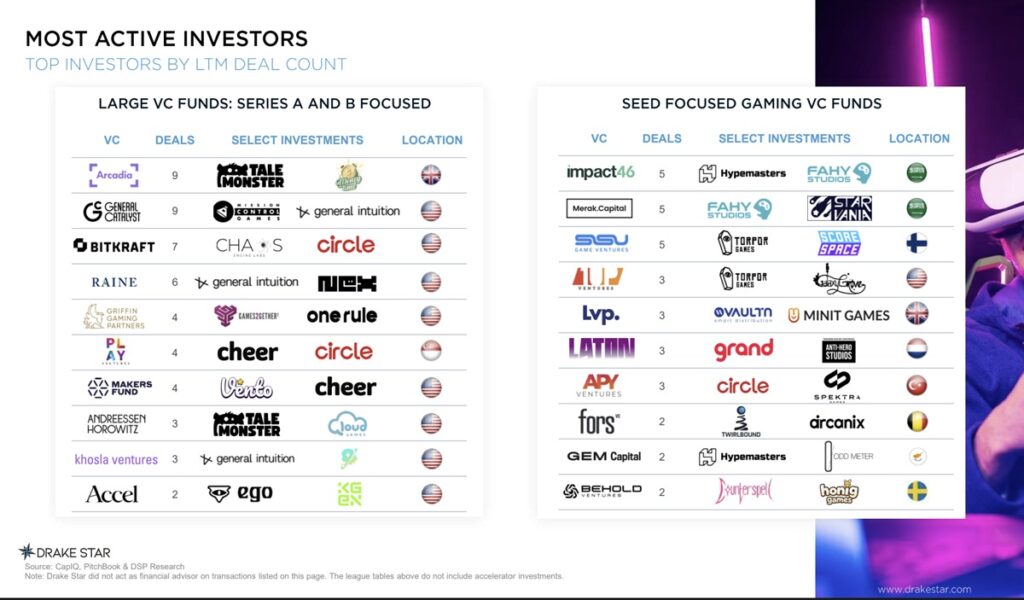
The most active venture investors by deal count include Arcadia with nine deals; General Catalyst with nine deals; Bitkraft with seven deals; Raine with six deals and Griffin Gaming Partners with four deals.
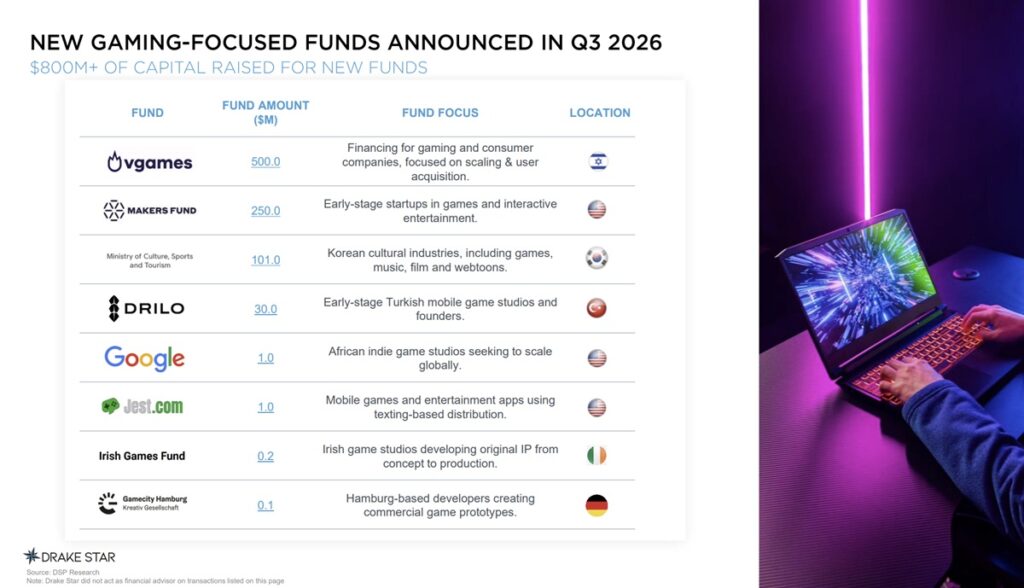
The new gaming-focused funds that raised money in the quarter included Vgames’ $500 million user-acquisition fund; Makers Fund’s $250 million early-stage investment fund; the Korean Ministry of Culture, Sports and Tourism’s $101 million fund; Drilo’s $30 million Turkish mobile game stud fund; and Google’s $1 million Africa indie game studio fund.
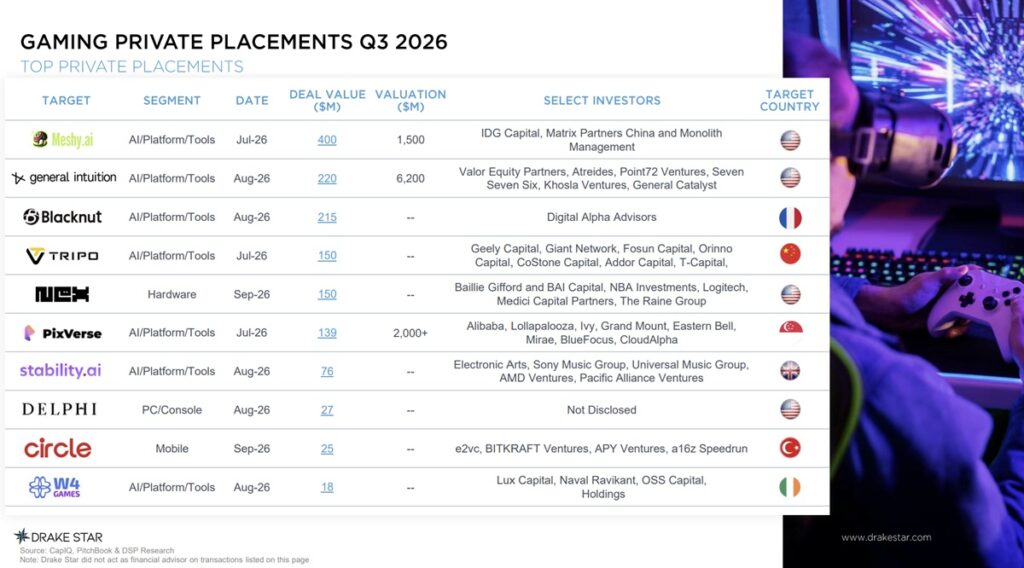
The biggest private placement deals of Q3 2026 were Meshy.ai’s $400 million raise; General Intuition’s $22 million raise; Blacknut’s $215 million raise; Tripo’s $150 million raise; and Nex’s $150 million raise.
Download the full report here for a deep dive on all the M&A, investment and public market activity for the quarter.